
Zihang Niu
AI Engineer @ Atlas Cloud
About
I am a Master's student in Applied Data Science at The University of Chicago, specializing at the intersection of Quantitative Finance and Machine Learning. My experience spans from high-frequency trading (HFT) alpha discovery to building large-scale AI infrastructures. At Redwall Taihe (HFT Fund), I engineered state-of-the-art predictive models (FactorVAE, GHMM) and architected time-series database pipelines to reduce backtesting latency. Currently, I am focused on leveraging LLMs & RAG for financial market analysis and seeking 2026 Summer Internship opportunities in Quantitative Research / Trading. Areas of Expertise: Alpha Factor Research, Time-series Forecasting, LLM Agents, Distributed Systems. Tech Stack: Python, C++, SQL (ClickHouse), PyTorch, LlamaIndex.
United States
New York
Computer Software
Generative AI, CoT, Deep Learning, Artificial Intelligence (AI), Machine Learning, High-Frequency Trading, Retrieval-Augmented Generation (RAG), PyTorch, ClickHouse, Quantitative Research
Experience
AI Engineer
Atlas Cloud

Quantitative Research Intern (Machine Learning Track)
Shanghai Redwall Taihe Fund Management Co.
Beijing, China
1. Infrastructure Optimization: Architected and optimized a distributed time-series database pipeline handling 5 GB daily high-frequency ticks, reducing query latency for backtesting by 17% using ClickHouse. 2. Factor development: Ingesting millisecond-level quotes and executions for 4,800+ equities. Developed and validated 1,200+ cross-sectional and microstructure factors, improving out-of-sample IC by 15% and cutting factor turnover by >20%. 3. Model Development: Engineered state-of-the-art predictive models(FactorVAE, GHMM) for alpha discovery, achieving 27% Sharpe ratio uplift and ensuring statistical robustness through Cross-Validation and backtesting.
Research Assistant
Institute of Mathematics and Systems Science, Chinese Academy of Sciences
Beijing, China
1. Enterprise Qualification Evaluation: Pytorch, Sklearn and other libraries are introduced for grading enterprise qualifications based on a total of 258 evaluation indexes in five dimensions, such as scientific and technological innovation, financial capital and compliance ability, etc., which are combined with the patent source data of the enterprises to be evaluated and the information related to the cases, etc., and the use of a large language model (GPT4.0 and Llama2-7B, etc.) and the Retrieval Augmented Generation (RAG) technique is utilized. RAG) technology for the hierarchical evaluation of enterprise qualifications.The addition of RAG significantly improves the model performance, and the evaluation accuracy increases from 65.2% to 87.5%. The paper is expected to be submitted for review in February 2025 to ICML. 2. Multimodal Sentiment Analysis - Stock Price Prediction: Using Large Language Modeling (LLM) and Retrieval Generation Augmentation (RAG) techniques, a multimodal deep regression model is built based on text and audio data from earnings conference calls of public companies (stage1: BiLSTM+). stage2: 2 Layer neural network) to predict the future stock price of individual stocks.
Investment Quantitative and Risk Management Intern
Taikang Insurance Group Inc.
Beijing, China
1. Quantitative strategy research and development: Based on Python libraries such as Pandas and Numpy, we analyze the effectiveness of various trading strategies (based on candlestick patterns) targeting SSE 50, CSI 300, and CSI 500 constituents, such as double-bottom strategy. Using TensorFlow framework, CNN and LSTM models are built to mine the latent effective factors in K-line charts, significantly improving the effectiveness of the strategies, with an average annualized Alpha of 13-16% over the period of 2011-2021. 2. VAR Calculation: Automate the updating of fund managers' weekly investment performance data using libraries such as Python Pandas, Numpy, etc. Calculate VARs for over 2,500 investment products using historical simulation methods to assist the department in post-investment risk management. 3. Deployment of AI Agent: Introduced RAG and LLM and assisted in the development of departmental intelligences, which automatically update the “Market Trends” and “Financial Hot Spots” sections on a daily basis.
Investment Assistant
Jiangxia Green Private Equity Fund Management Co.
Beijing, China
1. Industry Research: Specialized in equity investment in new energy photovoltaic field. He has participated in 10 investment projects, covering PV upstream silicon, silver paste, midstream battery cells, auxiliary materials and downstream UHV insulation materials and other sub-tracks, assisting the investment director to carry out industry research and completing 3 industry strategy outlooks. 2. Valuation Modeling: Participated in building market demand model. Measuring the CAGR of key business indicators and other data, taking into account the industry characteristics, policy impact and other factors, using discounted cash flow model (DCF), relative valuation analysis (EBITDA) and other methods to carry out valuation calculations for the proposed bid and make profit forecasts. 3. Investment strategy: conduct investment program research for the company to be bid. The analysis includes macro environment, business model, market pattern, industry scale forecast, industry concentration, bargaining power and financial status.
Education
University of Chicago
Applied Data Science
University of International Business and Economics
Economics
Zihang Niu's Contact Information
Phone
Find the Right Leads
Find Verified Contact Data

What LeadContact does well
Find verified emails, phone numbers, and decision-makers with 98% accuracy.

Find Leads
Find the right people by company, role, industry, location, and more.
925M+ professional profiles

Find Emails
Access verified email addresses for your target contacts.
657M+ emails

Find Phone Numbers
Get cross-validated phone data from multiple top sources.
239M+ phone numbers
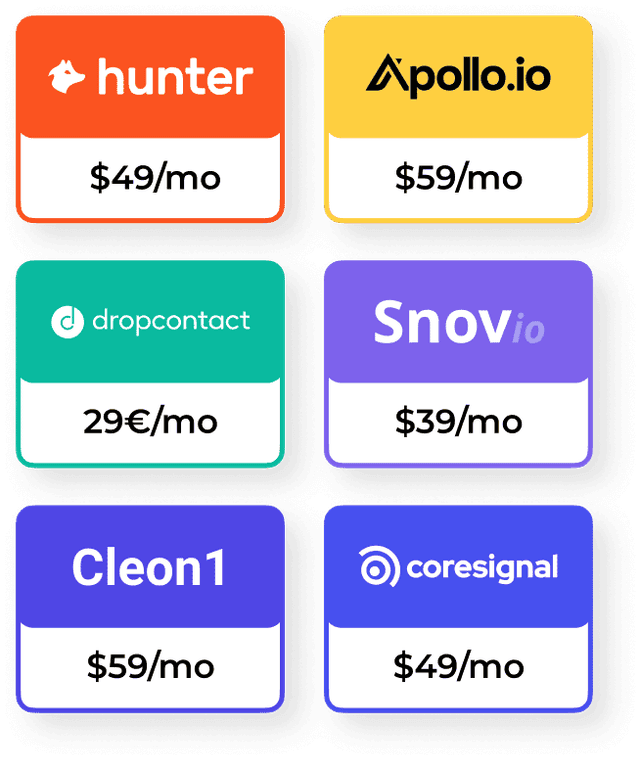
More Accurate. Lower Cost.
Find contact data in 1 tool with 98% accuracy
LeadContact integrates leading enrichment tools to deliver more accurate contact data—without paying for each one.

Great conversations start with the right contact.
It’s time to find yours.