
Kelvin Mason
What obtaining my Australian Credit Licence (ACL) means to borrowers. @ Buy Invest Live
About
LOANS MADE SIMPLE. I get it. When it comes to loans, there is a lot to know. My job - to compare loans from Australia’s biggest banks plus a range of over thirty specialist lenders to find the right loan for you. A tech-savvy customer demands a tech-centric broker. Today’s tech-savvy customer has created a marketplace that demands intuitive information and data gathering, faster response and processing times, and transparency of the application process, wrapped up in an easy and readily accessible digital solution. Deciding who is best to partner with for safety, growth and your end-game has never been more important. How can I Help? First Time Purchase … including Family Guarantees Next Time Purchase ... Loan Structure, Speed and Expertise Refinance & Renovation ... % Rate & Save $, Debt Reduction Self Employed ... From Startup to growth, Asset finance & Factoring Property Investors ... Equity Release, % Rate, Correct Structure Property Developers … Big 4 - Second tier - Private funders
Australia
Greater Sydney Area
Financial Services
Debtor Finance, Trade Finance, Mortgage Broking, Specialist Lending, Development Finance, Business Strategy, Product Management, Business Development, Strategy, Go-to-market Strategy, Marketing Communications, Business Planning, Competitive Analysis, Leadership, Strategic Partnerships, Business Alliances, Business Relationship Management, Finance Strategy, Investment | Property Strategy, Investment | Dual Income Property
Experience
What obtaining my Australian Credit Licence (ACL) means to borrowers.
Buy Invest Live
Sydney, New South Wales, Australia
► What is an ACL? An Australian Credit Licence is a certification issued by the Australian Securities and Investments Commission (ASIC) that allows individuals and businesses to engage in credit activities. This includes providing credit assistance, suggesting credit products, and acting as an intermediary between lenders and borrowers - services brokers normally need to do via an aggregator (who would hold the credit license). ► The Journey to Obtaining an ACL Obtaining an ACL is no small feat - the rigorous process ensures that only qualified professionals are granted the licence, maintaining high standards in the industry. The process involves: 1. Extensive preparation and documentation 2. Demonstrating compliance with responsible lending obligations 3. Proving financial capability and organisational competence 4. Undergoing thorough background checks ► Having an ACL brings several advantages to borrowers Increased Options: With direct access to a wider range of lenders and products, I can now offer more tailored solutions to meet individual borrower needs. Enhanced Protection: ACL holders are bound by strict regulatory requirements, ensuring borrowers receive ethical and compliant service. Personalised Service: As an independent licence holder, I can provide more personalised attention and advice, free from the constraints of working under a larger organisation. Specialised Lending: The ability to work directly with multiple lenders allows me to secure loan products not widely available. ► Obtaining my ACL is just the beginning. I'm excited to leverage this new capability to provide enhanced services and create better outcomes for borrowers.
ACCOUNTANTS & CPA's
Buy Invest Live

Sydney, New South Wales, Australia
► Accountants can completely change your business! Accountants are the most trusted profession, because they demonstrate independence, objectivity, and commitment in their relationships with their clients. When people are turned down for loans by traditional lenders they look for alternatives, and seek recommendations from people whom they have trust in. ► People are different - work is diverse - Finance Brokers get it. Research found that 3.6 million or 18% of Aussies have been turned down for a loan by a financial institution and > 54% were unaware that there were options. As a result, a large proportion of Australians are being locked out of the financial system, unable to access the support they need to meet their financial goals. Brokers now write > 59% of all residential loans - including for business purposes, and there is very good reasons for it , our advice is very valuable and also impartial. ► Collaboration between Accountants and Finance Brokers. The tightening credit environment means the number of people needing alternative lending solutions is only growing, and finance brokers are ready to assist clients looking for alternatives. Accountants, having spent many years building up your business, you wouldn’t want to jeopardise your reputation or clients’ financial security by referring them to just any finance broker. Let’s start a conversation! ► Common Situations I can help with. Interested to know more? I have a selection of one page guides that highlight the type of clients I can help with alternative lending.
CONSTRUCTION & RENOVATION
Buy Invest Live
Sydney, New South Wales, Australia
"… in 2018, 90% of our clients had delays with credit or were unable to secure credit” (Leading Sydney Builder) - and its not changed since! ► How to fund a renovation to your home - If you are knocking down and rebuilding your home, a construction loan might be the most suitable for you. However, if you only intend to renovate your home, you could always use the equity in your home to fund the renovations, a line of credit, even a personal loan. ► What's your preference - This might sound surprising but the decision to renovate or rebuild can depends upon your nature and preferences. If you are the kind of person who is attached to the history of your house, you’d most probably prefer to renovate the house while keeping its original structure intact. However, if you like all things new and shiny, a rebuild is what would suit your taste better.Of course, despite your personal tastes, practical considerations such as cost and market value will determine your final choice. The end result is to have a comfortable and good-looking house that is in sync with your lifestyle. ► Fixed Price Building Contract (FPBC) - To reduce risks of cost blowout most lenders requires a FPBC. Payments are made in stages, so the value of your home or investment is evident. Additionally we need a copy of the inclusions/specifications, builder public liability insurance and for major works, council plans. ► How to Finance Construction & Renovations - Not all lenders are equal when it comes to construction and renovation finance. Thats why brokers (like me) think about and look for finance solutions 24/7.
INVESTMENT || in Property
Buy Invest Live
North Sydney, New South Wales, Australia
► How many properties do you need to retire? Possibly only 2 - full paid off - depending on property type. “If you have not hit 40 yet, you are probably not thinking that far ahead, If however you have passed 40 and especially 50, there is now no time for mistakes with your finances or investments.” ► Cash Flow | Simple, yet Powerful The strategies I share are based around Cash Flow, they are simple yet powerful, and are designed to answer 2 key questions: - How much longer you expect to work? - How much guaranteed income you have? Did you know - that you can insure your cashflow? Leading Insurance companies charge 5%. ► Affordability | both for the Investor the renter Property investing should be for the medium to long term. There are costs to acquire including stamp duty and costs and time to sell. So I don't advocate interest only repayments, wait for capital growth, and sell, as an investment strategy. What about finding a suitable property that can be purchased and paid off - even better if the yield is high enough to provide positive cash flow to repay your home loan. Did you know - that you are are better off owning two investment properties worth each than one worth twice the price! ► Correct Property Type | Dual Income This leads on to what is the correct property type that puts together a plan to reduce debt, using affordable housing.
INVESTMENT || Finance
Buy Invest Live
Sydney, New South Wales, Australia
► How to improve Cash Flow as a Property Investor through Interest Only (IO) loans When an investor determines their long-term investment strategy and objectives, the loan structure is an important factor to consider as it can significantly impact the overall success of the investor’s portfolio. Many investors might shy away from an interest only loan due to a fear that they will fail to chip away at the entire mortgage, however if used correctly, this option is highly beneficial for an investor’s cash flow. ► Lower Monthly Commitments An interest only loan requires the owner to only pay the interest charged on the loan each period, rather than making repayments towards both the principal and the interest. Using a home loan interest rate of 5% as an example, the monthly repayment on a $300,000 mortgage over 25 years would be approximately $1,754 per month for both principal and interest. However if you were making interest-only payments, the monthly cost would drop to approximately $1,250 per month. That means more money in your pocket each month. ► Improve Cash Flow Lower overall commitment, and the payments you do make will help your cash flow and improve your ability to reinvest. NB- Property owners could look at putting this additional cash towards a loan that isn’t tax deductible – such as their home loan to help pay it off more quickly. ► Tax Deductible Any repayment that is made on the interest of a loan is tax deductible. However, payments on the principal are not tax deductible. This means that savvy investors can maximise the tax advantage through an interest only loan. ► Build an Asset Base Interest only loans allow you to build a bigger asset base.
INVESTMENT || Strategy
Buy Invest Live
Sydney, New South Wales, Australia
► Investment Strategy Everyone wants to be mortgage free, but now more than ever it is financially crucial that you do so as quickly as you can. The reasons why you are investing, are the same reasons why you must become mortgage free faster - paying off the family home and wealth creation for retirement. The first step is simply to get an idea of where most people go wrong so you can get it right. ► Debt Reduction If your home is not paid off, then this and any consumer debt (credit cards, car or personal loans, HECS) are the first to be paid out. As a general rule, Investment loans be Interest Only so you can maximise payments off your home, first, before repaying your investments.Becoming mortgage free faster means that you need to grow the equity you have built up in your home – this is because you will later use the equity you have built up to create additional sources of Cash Flow to accelerate repaying your home. ► Preserve Cash Investing builds both your Equity your Cash Flow. In most instances, borrowing the maximum possible and paying LMI (lenders mortgage insurance) conserves your cash. Loan costs (inc LMI) are deductible over 5 years. ► Cash Flow Positive If you can achieve an additional $100 - $150 per week from an investment property, how much quicker can you pay out your home loan? (average 6-8 years)Remember we are not talking about adding an expense, this is using equity to create additional income to repay non-deductible loans. How much sooner is it possible to pay off my home loan - without affecting my lifestyle? ► Lender Policy Let's determine your net income, deposit/equity and right lender. A Preliminary Assessment can show your pre/post loan cashflow and best lender options.
NDIS Finance 80-90% || No external servicing required
Buy invest live
Sydney
► Did you know investing in NDIS properties is not just smart for your wallet but also benefits the government? Instead of burdening the system, these investments help NDIS participants live independently, moving them out of healthcare/aged care and into their own space. ► Here's the scoop: - NDIS investments can often be financed through construction loans or even your SMSF (though it's about 10% pricier). - These properties are hot and sell out fast! What's available today might be gone tomorrow, but don't worry, there's always something new on the horizon when you're ready to dive in. ► Finance Essentials: - Got a credit score of 650+ with no defaults? You're in! - Enjoy up to 80% financing. - Rates are at 8% interest-only during construction, then shift to 7.2% P&I over 25 years. - Expect standard fees around $12,560, with construction fees at 1.5%, and your accountant can help set up a Corporate Trustee. - Alternative finance available to 90%, taking into account current financial situation. ► NDIS Property Perks: - Fully equipped and NDIS compliant homes. - Includes all NDIS registration and SDA approvals. - Features include a 3-bedroom setup with two rooms designed for High Physical Support and a carer's room. - NDIS could net you about $180K a year in rent for 2 rooms according to the SDA price calendar for 2023-2024. ► Home Highlights: - Safety first with commercial-grade fire sprinklers. - Spacious with 3m high ceilings and wider entry doors. - Durable, vandal-proof fixtures and fittings. - Extra security with external escape doors, intercoms, and security cameras. - Eco-friendly with solar panels and battery backup. - Plus, sensor lights, wider internal doors, slip-resistant floors, and multi-headed split system for comfort. ►Keen to learn more? Let's chat! ►PS: Interest rates and lending conditions noted are correct as at 01/03/2024.
Unlocking Equity in Retirement: Understanding Reverse Mortgages
Buy Invest Live
Sydney
►In Australia, 89% of those 65+ own their homes. For financial ease in retirement without selling, consider a reverse mortgage, offering access to your home equity. ►Key Benefits: - Lifetime Stay: Remain in your home. - No Negative Equity: Loan won't exceed home value. - Deferred Repayments: No payment until the loan's end. ►Eligibility: - Age: 60+ (couples: one over 60, the other 55+). - Loan-to-Value Ratio (LVR): Age minus 40 determines LVR (e.g., age 70 = 30% LVR). - Security: Reduced LVR for non-primary residences. ►Reverse Mortgages Explained: Designed for seniors, these loans release equity for a better retirement without monthly repayments. Debt is settled upon property sale. ►Uses: Fund home upgrades, travel, or medical expenses. You keep ownership and benefit from value increases, staying indefinitely. ►Features: Receive a lump sum, income stream, or cash reserve. Repay early without penalties for added flexibility. ►Addressing Retirement Gaps: With longer lifespans, the pension might fall short (annual pension: $22,937 for singles, $34,580 for couples). Reverse mortgages offer an alternative to enhance retirement living. ►Compliance and Advice: Compliant with NCCP's Best Interest Duty, considering financial impacts and aged care needs. Seek advice from professionals; family input is encouraged. ►Take Action: Consider unlocking your home’s equity with a reverse mortgage for a secure retirement. Let's discuss your options.
Why and how to invest in SMSF
Buy Invest Live
Sydney
► Self-Managed Super Fund (SMSF) lending is increasingly popular, providing up to 80% financing for residential and 70% for commercial properties. Notably, some lenders offer pre-approval even before an SMSF is fully set up, subject to certain requirements like a minimum deposit and maintaining a financial buffer. Loans are primarily "stand-alone", relying on the SMSF's income and expenses, though some flexibility exists for including personal financial support in case of servicing issues, up to a $27,500 annual limit. ► Investing in National Disability Insurance Scheme (NDIS) properties attracts investors with its high return potential, often requiring a construction loan for properties purchased before completion. This investment strategy necessitates a significant SMSF deposit, around 35%, limiting some investors. ► The appeal of SMSF property investment : - Control and Flexibility: Offers control over investment decisions, enabling tailored portfolios. - Diversification: Provides a way to spread risk across different asset types, enhancing portfolio resilience. - High Return Potential: Capital growth and rental income opportunities are significant, especially in strong markets. - Tax Advantages: Benefits from lower tax rates on capital gains and rental income. - Asset Protection: Safeguards assets from personal financial downturns. - Estate Planning: Allows for efficient asset management and transfer. - Leverage: Enables borrowing to make larger investments than might otherwise be possible. ► Despite the benefits, investing in property through an SMSF involves navigating complex legal regulations, potential liquidity issues, and the responsibilities of property management. Therefore, consulting with financial and legal professionals is crucial to aligning this investment strategy with overall financial goals and ensuring compliance with superannuation laws.
Why Choose a Mortgage Broker Over a Bank?
Buy Invest Live
Sydney
► Unlock the Full Potential of Your Mortgage with Expert Guidance ► Navigating the vast sea of mortgage options can be daunting without the right expertise. That’s where a seasoned mortgage broker comes in—a pivotal resource who not only understands your financial landscape but also provides access to an extensive array of lenders (62+). ► Why Choose a Mortgage Broker Over a Bank? - Broader Access: Enjoy a wide range of loan options from large banks to non-traditional lenders and mortgage managers. - Personalised Service: Our brokers tailor the best finance deals to fit your unique needs. We do the legwork, ensuring you're paired with the most suitable lender without the hassle. - Competitive Rates: We facilitate easy comparisons of rates, fees, and charges, striving to secure rate discounts that go beyond what lenders typically advertise. - Informed Decisions: Leverage our industry experience to make choices with confidence, knowing you're well-informed every step of the way. - NO Cost to You: For residential and investment loans, our services are free to you. We're compensated by lenders, which motivates us to maintain exceptional service and advice. - Flexibility and Dedication: Our brokers are accessible after hours, ready to go the extra mile. We guide you through the loan application process, advising on necessary documents and paperwork. ► Our mission is clear—to guide you at each step, providing expert lending advice and ensuring we act in your best interests. Reach out today to experience dedicated, personalised mortgage advice tailored just for you.
Unlock Tax Benefits with Property Investment in Australia!
Buy Invest Live
Sydney, New South Wales, Australia
► Investing in property in Australia offers several tax benefits that enhance profitability and cash flow: - Negative Gearing: Offset property expenses that exceed rental income to reduce taxable income. - Depreciation Deductions: Claim depreciation on the building structure and fixtures to lower taxable income. - Capital Gains Tax (CGT) Concessions: A 50% discount on capital gains for properties held over 12 months. - Interest Deductions: Interest paid on loans for investment properties is tax-deductible. - Expense Deductions: Costs like property management, repairs, insurance, and advertising are deductible. - Travel Expenses: Deduct travel expenses related to inspecting and maintaining your investment property. - Prepaid Expenses: Deduct prepaid expenses in the current tax year to lower taxable income. - Borrowing Costs: Deduct borrowing costs, such as loan establishment fees, over the life of the loan or five years. ► FINANCE for INVESTORS ► As a Finance and Mortgage Broker, my expertise is in maximising your borrowing capacity, structuring loans for current and future investments, and obtaining pre-approval to secure your investment property with a 66W after due diligence and building and pest/strata reports. ► Borrowing as an investor generally increases borrowing capacity using rental income (most lenders use 80%), negative gearing, and borrowing up to 90% using interest-only repayments, assisting cash flow. ► In summary, investing in property in Australia offers significant benefits, including potential capital growth, regular rental income, and various tax advantages. Australia’s stable economy, robust legal framework, and high demand for rental properties make it a secure and profitable investment option.
Alternative Self Employed Lending Specialist
Buy Invest Live
Sydney, New South Wales, Australia
► As a finance broker working with businesses, I understand that one of the most significant challenges for new businesses is securing adequate capital. Many entrepreneurs face financial constraints due to tightening lending restrictions from major banks, leaving them unable to obtain loans at prime rates. ► Big 4 or Specialist Lenders - I focused on leveraging opportunities from specialist lenders to support borrowers who are often overlooked by larger financial institutions. These lenders provide alternative financing solutions for those who need them the most. ► Supporting New Entrepreneurs - Whether you're transitioning from an apprentice to self-employed, moving from full-time employment to contracting, or need funding for business expansion, I can assist you in navigating the financial landscape. I offer guidance on securing funding for new contracts, equipment, or vehicles, tailored to your business's stage of development. ► Specialist Lending Solutions - Specialised loans include near-prime, low-doc, and no-doc lending options, which are rapidly growing segments in the loan industry. My clients include investors, the self-employed, and families, all of whom can benefit from customised lending solutions that address their unique circumstances. ► Comprehensive Business Banking Services - I provide a range of business banking services, including term loans, overdrafts, bank bills, foreign exchange, debtor financing, factoring, and short-term lending. ► Customised Lending Policies - I work closely with clients to determine their business borrowing capacity, considering current and future needs, security, and cash flow fundamentals.
PROPERTY DEVELOPMENT
Buy Invest Live
Sydney, New South Wales, Australia
► As our property markets slow, more investors are interested in becoming involved in property development as a way of creating capital growth. ► What is required to be a successful developer is good education, proper planning and a good team around you, and you can potentially end up having high growth properties that deliver strong cash flow and good tax benefits. ► As a property developer, finance and what the banks look for when lending for development projects, is very different to how they assess financing a simple "buy and hold” investment. ► Lenders generally class 2 or 3 build projects as “residential” developments and use less stringent lending criteria for this type of project, whereas with larger developments they may require a greater percentage contribution of equity or a level of pre-sales. ► Typically, you will need to provide 20% of the funds for a 2 dwelling project and 30-40% for larger projects. ► Banks remain the major source of funding for developers, however many of the major players are tightening their lending criteria. ► As a result, second tier banks, private funders and joint venture funders are increasingly becoming a popular alternative for some developers. ► Proficient mortgage brokers with the right expertise and knowledge can assist you when it comes to obtaining development funding.
RESIDENTIAL & COMMERCIAL Finance
Buy Invest Live
Sydney, New South Wales, Australia
► LOANS MADE SIMPLE. I get it. When it comes to loans, there is a lot to know. My job - to compare loans from Australia’s biggest banks plus a range of over thirty specialist lenders to find the right loan for you. A tech-savvy customer demands a tech-centric broker. Today’s tech-savvy customer has created a marketplace that demands intuitive information and data gathering, faster response and processing times, and transparency of the application process, wrapped up in an easy and readily accessible digital solution. Deciding who is best to partner with for safety, growth and your end-game has never been more important. ► How can I Help? First Time Purchase || Provide Education & Finance Options - 98% and 105% (family guarantee)Next Time Purchase || Loan Structure, Speed and ExpertiseRefinance || % Rate & Save $, Debt Reduction, Cash Out (debt - self employed - investment)Self Employed || From Startup including Lo Doc - Asset - FactoringProperty Investors || Equity Release, % Rate, Correct Structure Property Developers || Small - Medium - Large "Buy and Sell" Projects
FIRST HOME BUYERS
Buy Invest Live
Sydney, New South Wales, Australia
► First Home Buyers rock! We are seeing the highest level of first home buyers since 2010. Although lending criteria is tight, there are many first home buyers out there taking the plunge into property ownership – and you could be too! Still, it pays to be cautious; understand your borrowing capacity and learn your deposit options (including your own deposit or one from mum and dad). ► Dont start till you sit down with a professional - Buying your first property is a big step and often a daunting one with many questions to be answered – like "how and when should I buy?" and "can I really afford it?" ► What’s The Secret To Buying My First Home? - Getting Started! ► Decide what you can afford - Look at your income, liabilities and living expenses, now or at any time in your FHB journey. You’ll feel a sense of confidence as I work with you through all aspects of your loan application, from your decision to buy a home, right through to being handed the keys. ► Saving for it - Saving for a home loan or mortgage isn’t glamorous but it has to be done. Not sure where to start budgeting? ► (or) Family Guarantee - A home loan guarantor provides security to the bank by using the equity in their own property (up to 30% of the buyer’s property value) so the FHB can avoid costly Lenders Mortgage Insurance (LMI). ► FHO Grant (each state offer is slightly different) - There is also a stamp duty concession for first home buyers of new or existing properties valued between $650,000 and $800,000. ► Get your finance pre-approved - Do this before you start looking. Don’t risk missing out on a great property because you haven’t got your finance organised.
LITE DOC & NO DEPOSIT || ASSET & EQUIPMENT FINANCE
Buy Invest Live
Sydney, New South Wales, Australia
► If you have been in business for 2 years, own or have mortgaged property and have a clear credit file, you can expect to have access to funds up to $50,000. If you do not own property, you may be able to access up to $20,000. Just starting out - there are other solutions including a part deposit. What equipment do you need? Computers, Office Equipment, Security Equipment, Specialty Industry Equipment, Trucks, or any equipment for your business. ► Self employed finance solutions - non-conformingThe bank’s strict lending criteria makes applying for and securing a self-employed loan time consuming and overwhelming, but there are alternatives. While predominantly plant, equipment & heavy vehicles, we can lend to business generally including : - ATO arrears - Veda defaults - Cash flow / Working capital - Start ups - Other lenders declined applications - Specialised or older equipment ► Funding from $25k to $750k. Generally the LVR is 75-85% however alternative security can be arranged by charge over unencumbered vehicles, plant or equipment or mortgage. - Purchasing a Business - Commercial vehicles - Heavy machinery finance - Creditor payments - Manufacturing equipment - Go-Rent, Go-Grow. Go-Own ► Unique to the marketplace, the Go-Rent. Go-Grow, Go-Own equipment funding solution allows you to save your hard-earned working capital, rather than spending it on depreciating assets. If you exercise your option to buy during the first 12 months, we reduce your purchase price by 75% of the net rent you’ve already paid. ► Who says you can’t make your rental dollars work for you?
COMMERCIAL PROPERTY & BUSINESS FINANCE
Buy Invest Live
Sydney, New South Wales, Australia
► Commercial Finance is a multi-faceted field and no two projects are alike - This includes commercial offices, industrial factories, retail shops and construction, and can involve any number of elements from working capital requirements and initial funding of a particular business or enterprise through to accessing the right finance method for purchase of plant and all equipment. ► When considering a commercial financing proposal, we take into account the financial requirements and match that to the appropriate lender and facility type. We also consider the current % rate climate, potential exit strategies and possible complications that may arise in each scenario – all to get the best possible result. ► If you’re purchasing, developing or expanding a business, don’t make the mistake of consulting your bank, seek the advice of an independent operative who can assist in structuring your finance proposal and can assist in securing the lowest rates available through a bank or another lender. ► Specialised Funding? - For example, a building that has been specifically built for a childcare centre, a medical centre, hotel, agriculture etc. It also include backpacker accommodation, petrol stations, resort style accommodation and wedding reception venues. These are classified as "specialised". ► There are some specialised buildings such as restaurants where a funder could ask the valuer for an “alternative use” valuation for that property. This means that the property could be converted to say offices and in these cases a specialised building can be financed in the same way as a commercial office or commercial factory. ► Another example, hotels and motels (leasehold and freehold) can be financed to 65% of the real estate value or around 65% of the combined real estate value, business component and any liquor/poker machine licenses. ► Let's chat about next commercial finance or development project and create a tailored commercial finance solution.
MORTGAGE BROKER || FINANCE BROKER
Buy Invest Live
► Gaining access to an experienced mortgage broker is an invaluable resource when looking for finance. The broker will assess your financial situation and has access to a much wider range of loans (35+). Fundamentally, a good broker will be able to advise you on the pros and cons of various loans. They will advise the best way in which to structure your loans and the risks associated with proceeding at any stage. ► There are a number of good reasons to use a mortgage broker instead of a bank: - Access to loans from lenders that include the large banks, plus other non-traditional lenders and mortgage managers. - A broker will find the best finance deal that meets your needs. The initial due diligence that a broker undertakes not only gives you access to a large range of loan options without you having to do any of the legwork, it will also ensure you are matched with the most appropriate lender for your individual circumstances. - Access to loan rates, fees, and charges that enables an easy comparison of loan costs. Where possible, a broker will also do their best to obtain discretionary rate discounts over and above what the lender may advertise. - The broker’s experience in the mortgage industry will help you make informed decisions and allow you to feel confident throughout the process. - For residential home and investment loans, the broker does not charge the client. The broker receives a commission from the lender at settlement on the loans they write. Therefore it is in the broker’s best interest to ensure they offer great service and advice to their client. - A broker is accessible after hours and often more willing to go the extra mile for you. We will walk you through the loan application and advise what documents and paperwork we need to submit with your application. ► Our mission is to guide you each step of the way and provide you with expert lending advice. We will always act in your best interests and be there when you need us.
CREDIT ADVICE and LENDING STRATEGY
Buy Invest Live
Sydney, New South Wales, Australia
► Borrowing money is different from lending it out. The Lender wants to make money from you at the lowest possible risk. They manage risk by having Lending Guidelines and they buy your business by giving you an interest rate they can get away with. ► Banks manipulate Lending Guidelines that will give them the clients they want and keep abreast of their exposure to the various markets. They can change their calculators, increase living expenses, increase the weighting for existing debt, and even reclassify security types. All of these measures will reduce the borrowing capacity without you ever knowing. ► What the public sees is the interest rate. Should you let the Bank decide if you can be borrowed or not? - Asset Finance | Car, Truck, Equipment & Machinery - Lease / Chattel Mortgage. - Cashflow Solutions | Debtor & Trade Finance, Unsecured lending. - Credit File | Defaults - Debt Consolidation - Bad Debts - Part IX - short term finance. - Declined | 18% of Aussies have been turned down for a loan by a financial institution and > 54% were unaware that there were options. - Equity | Release equity for Business / Personal / Debt Consolidation. - Family Guarantee | To help families assist their children in the property market. - Investment | IO lending up to 10 years. Using multiple lenders to achieve new lending. - Refinance | Did you know that 85% of borrowers don’t know their home loan rate. A small 0.5% change on a $500k loan could reduce your loan by 4.5 years. - Self Employed | 26% of Part-time or Self-employed were declined - options starting from 1 day ABN. - Strategy | Having a sound finance strategy, understanding the risks, and having an exit strategy is key to long term success. ► 60+ Lenders | There are 3 parts of lending, including Deposit / Net Income / Policy. I review over 50 policies when reviewing lending options and these along with the correct strategy can make the difference between approval or declined.
SPECIALIST LENDING
Buy Invest Live
Sydney, New South Wales, Australia
► Near Prime lending is currently the fastest-growing segment in the loan industry. While circumstances may differ from those of Prime customers, the clients’ fundamental needs remain the same. Too often clients arrive with multiple credit hits on their files due to being steered in the wrong direction previously. It’s not simply limited to people who’ve had a credit event. Investors, the self-employed and families, to name a few, are all potential clients who can benefit from a specialty lender. ► When you don’t tick the boxes; - Didn’t meet LMI requirements - Didn’t pass credit scoring - Have been declined before - New Australian permanent residents ► When you need a flexible solution; - Multiple debts to consolidate - Need to pay out business debt - Need to pay out a tax debt - Need cash out for business reasons ► When you have problems in your credit history; - You’ve been discharged from bankruptcy - You have late payments or mortgage arrears - You have defaults or judgements - You have Part IX & X debt agreements ► When you can’t provide traditional documentation; - You’ve been self-employed for less than 12 months - You are ABN registered for only 6 months - Your income is casual or part time employment - You receive income in the form of family payments or child support
Mortgage & Finance Broker
Loan Market
Sydney, New South Wales, Australia
► Leveraging Loan Market's extensive lender panel, I've been delivering tailored lending solutions since 2020, now operating under my own Australian Credit License (ACL). My expertise lies in securing loans for diverse borrower profiles, combining market insights with personalised service to help clients achieve their property and finance goals. Key Areas of Expertise: ► BUY - Guiding first-time homebuyers through the mortgage process - Negotiating favourable terms for owner-occupiers upgrading or downsizing - Facilitating seamless transactions for property investors ► INVEST - Structuring loans for residential and commercial investments - Advising property developers and builders on financing strategies - Arranging SMSF property investment funding ► LIVE - Unlocking home equity through strategic refinancing - Sourcing competitive rates for debt consolidation and renovations - Crafting bespoke solutions for unique properties (rural, eco-homes)
Local Home Loan & Investment Specialist
realestate.com.au Home Loans
Sydney, Australia
Its different at the different stages and ages of your life - with most people starting their property journey by buying their home - others start by RentVesting. To get started, we should have a conversation ... ► FIRST HOME OWNER |Llooking to start and own your own home? There are many ways to assist, including; Family Guarantees and 98% finance. (* NB. dependent on servicing and other lender policy - just ask). ► PURCHASE | Started looking at properties? Lets get you pre-approved so the unconditional approval process is short, and you can use a 66w to negotiate (if you are not sure of property value or time poor, consider using a buyers agent). ► INVESTING | Investing is around finance structure, generally using equity, and maximising your cash and cash flow. We can have a conversation around rental return, negative gearing, capital growth, depreciation, positive cash flow and exit strategy. ► UPSIZING | Purchasing another home before selling your current home? I can assist with bridging loans or deposit guarantees - and compare lender options for you. ► DOWNSIZING or RETIRING | We can talk about swapping security or best finance options based on the outcome you need. ► REFINANCE | Did you want to save money or better still, pay out your home loan sooner? Did you know, investing in property, using your equity, is another way to assist and reduce repayment time and can be done without affecting your lifestyle. ► DEBT REDUCTION | Get rid of the credit cards, payout the car or HECS, this can be part of a structured Refinance. ► SELF EMPLOYED | Having an ABN is not an impediment to finance - and there are finance options from 1 day ABN (more costly) to 2 years plus and owning or paying off a home loan (which can be standard residential rates). Need cash out for tax or business? Kelvin Mason is a credit representative (469562) of BLSSA Pty Ltd (Australian Credit Licence 391237).
Business Development Manager
Aniluin Distribution
Sydney, Australia
► Aniluin are a wholesale distributor of POS and AIDC products. Our product range includes receipt printers, barcode scanners, cash drawers, label printers, cash registers, rugged PDAs, touch screen PCs and LCDs, scales. ► Aniluin supplies brand name vendors such as Epson, Zebra, Casio, CAS, Honeywell, Motorola and Datalogic; along with exclusive vendors including Nexa, Point Mobile and TSC. ► Aniluin are a "hands-on" distributor and we welcome any chance to showcase our products and for you to experience our service.
Product Manager | Data Capture | Scanning & Mobility | Wifi
Goodson Imports
North Ryde
► Goodson Imports distribute Hardware Technology to Resellers and ISVs. Solutions for POS, Hospitality, Field Sales & Service, Warehouse & Distribution, Health, and Transport & Logistics. ► My role is vendor and product selection, sell-through, forecasting, training, corporate presentations, and marketing. ► Each reseller, while competing amongst themselves, has a unique offering to the market, and through selected products offerings, I look to assist each to grow their own niche customers.
Country Manager for ANZ
Honeywell
Sydney, Australia
► Honeywell manufactures Barcode Scanners and Rugged Mobile Terminals. I focused on channel selection and growth as well as sales support, logistics and debtors. ► Being the first local country manager, it was an action filled time working with Distributors and Resellers to evangelise the Honeywell product offerings. ► Apart from fulfilling sales and business development roles I was responsible for pre and post sales support, logistics, debtors, web customisation.
Business Solutions Manager
AirData
Pymble, NSW
► Business Development focused on new business. IntelliTrack Stocktake, Asset Tracking and Warehouse Software solutions. Custom applications across freight, manufacturing, retail, warehouse customers. Hardware solutions including Symbol, Cisco, Zebra.
Director
Barcode Direct
Dural, NSW
► Barcode scanner, printer and consumables reseller. Our target markets included the hospital and medical markets, library and councils including records management, as well as point of sale, and light industrial. ► My key role was to develop the sales and marketing function. By staying focused on the key vertical markets and due to extensive knowledge of the industry I was able to create significant sales within a short period of time.
CEO
Zones, LLC
Pymble, NSW
► I was responsible for hiring and training a new sales team, and restructuring the management team. As part of a global initiative, I implemented Mozart CRM, with JDE financials on an AS400. This involved conversion, customising screens and reports and ultimately training in all aspects of use and reporting. ► The most enjoyable part of my role at MacZone was to assist the marketing manager to merchandise our 84p catalogue.
Sales Director
MacDirect
Pymble, NSW
► This included positions with Pica, MacDirect and MacWarehouse. ► Our PICA business consisted of sales of 16 and 21” Trinitron monitors to graphic designers. ► We launched MacDirect to provide Apple Macintosh software then sold it to specialist IT supplier MacWarehouse (MicroWarehouse).
Education
Macquarie University
Mathematics, Computer Programming
Completed 1 year part time. Career move an ensuing travel did not allow for past time study.
Kelvin Mason's Contact Information
Phone
Find the Right Leads
Find Verified Contact Data

What LeadContact does well
Find verified emails, phone numbers, and decision-makers with 98% accuracy.

Find Leads
Find the right people by company, role, industry, location, and more.
925M+ professional profiles

Find Emails
Access verified email addresses for your target contacts.
657M+ emails

Find Phone Numbers
Get cross-validated phone data from multiple top sources.
239M+ phone numbers
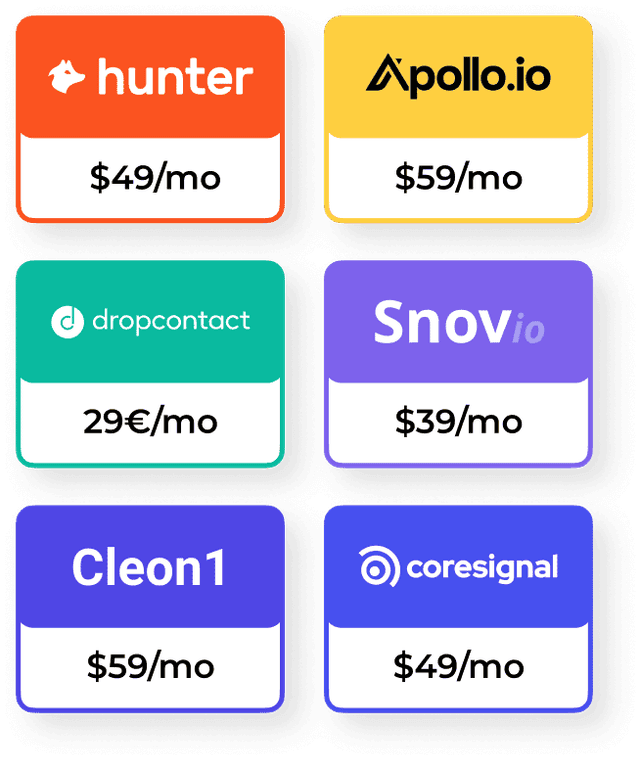
More Accurate. Lower Cost.
Find contact data in 1 tool with 98% accuracy
LeadContact integrates leading enrichment tools to deliver more accurate contact data—without paying for each one.

Great conversations start with the right contact.
It’s time to find yours.